
Blog
The New Affordability Strategy: Modular Homes, State “Attainable” Funding, and Credit-Score Modernization
6 min read
October 13th, 2026
Why affordability solutions are getting more targeted
Affordability has become a multi-front problem: not enough entry-level supply, too many homes that need work to be livable, and lending standards that can exclude borrowers who pay rent on time but lack a deep traditional credit file. Recent developments suggest the response is increasingly “toolbox-driven”—using specific mechanisms to address specific bottlenecks.
Production lever: modular and factory-built housing
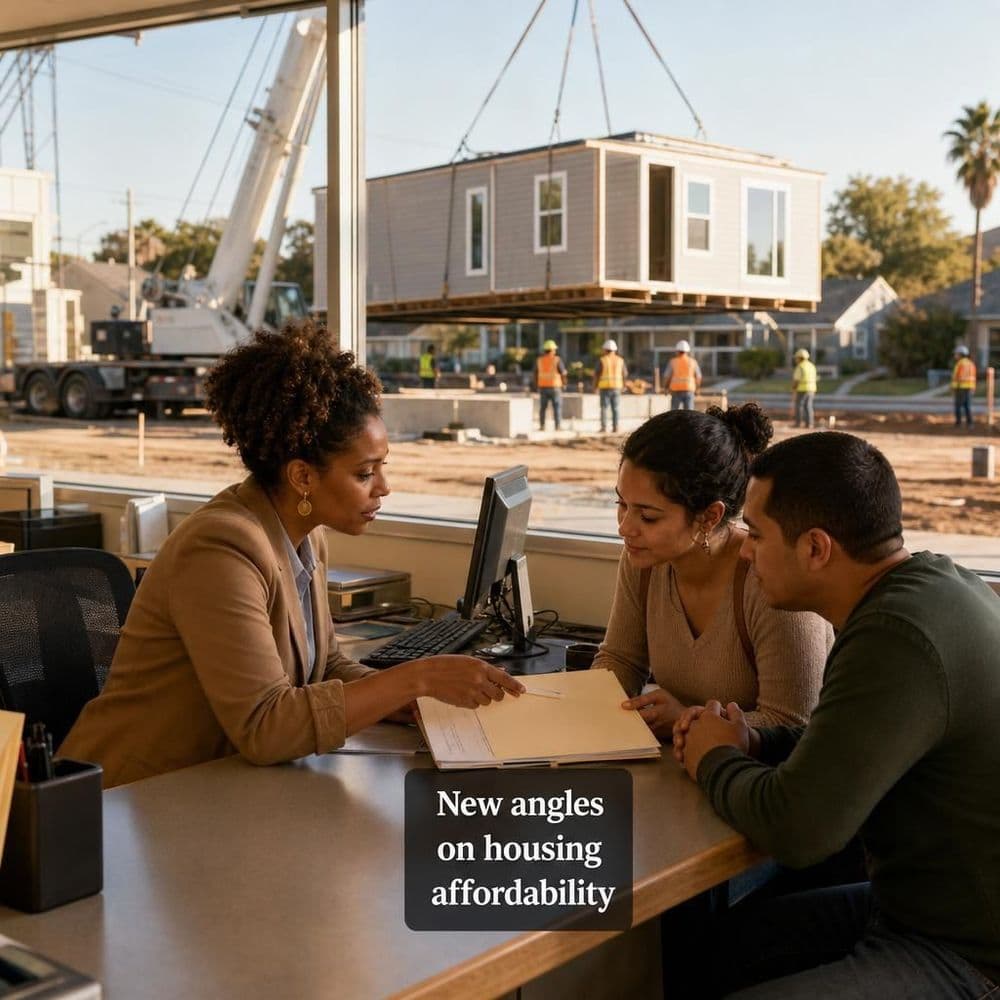
In Lorain, Ohio, a modular home went from an empty lot to nearly move-in ready in a single day, illustrating why off-site construction is getting renewed attention for attainable housing. The program described includes a no-interest mortgage structure and long-term property-tax relief, which directly targets the monthly payment hurdle for income-qualified buyers. [cleveland19.com]
At a broader level, factory-built options also run into local rules that make small homes hard to place. An opinion analysis notes that since 2020, legislation in six states has reduced zoning discrimination against manufactured housing, and that 31 states now limit localities’ authority to zone out this lower-cost housing type. It also cites research indicating that a single-section manufactured home built to HUD code can cost far less than a comparable site-built house, even after transport and foundation costs—highlighting why land-use rules (lot size, design mandates) are often the binding constraint. [governing.com]
Capital lever: state funding for attainable projects
Nevada’s latest housing funding round shows how states are trying to “unstick” deals by filling capital gaps and pushing projects to the finish line. The Nevada Attainable Housing Council approved about $38 million for 10 projects, expected to support 891 attainable homes and rental units, with a breakdown across land acquisition, multifamily rental development, and single-family/small-scale development categories. The state also described a leverage expectation across the portfolio—an attempt to stretch public dollars into larger project pipelines. [news3lv.com]
Credit lever: new scoring models and mortgage access
On the demand side, mortgage access is being reframed around modern payment behavior. A Realtor.com report describes a push to modernize credit scoring by encouraging the use of VantageScore 4.0 alongside models like FICO 10-T, which can incorporate rental and utility payment history in underwriting. The article notes claims that this could help millions of borrowers qualify, particularly those with thinner traditional credit files. [realtor.com]
The same coverage also flags lender concerns: different credit-score models are not interchangeable, and analytics on large loan datasets have found small average score differences but potentially meaningful divergence in default performance at the lower end of the credit spectrum—meaning lenders may need separate thresholds and pricing calibration. [realtor.com]
Making older homes financeable: renovation loans
Another increasingly practical affordability tool is the renovation loan. A HousingWire column argues that many lower-priced homes need repairs, shrinking the inventory that first-time buyers can actually use without substantial cash. Renovation products like FHA 203(k) and conventional renovation loans can bundle purchase plus eligible repairs, potentially expanding the set of homes buyers can compete for—especially where investors target fixers. [housingwire.com]
What to watch next
The big question is execution. Funding allocations matter less than how quickly projects can break ground and deliver units, and credit-model changes matter less than whether lenders can operationalize them without distorting risk pricing. Over the next several quarters, watch how local land-use rules adapt to factory-built options, how state “attainable” programs measure delivered units versus awarded dollars, and whether credit-score modernization translates into sustainably higher approval rates for first-time buyers without rising delinquencies. [news3lv.com] [realtor.com]
Comments